You walk through the front door, and your heart skips a beat.
The morning light floods across the living room floors. The kitchen has the exact island layout you envisioned. You can already picture your morning coffee on the back patio. Your stomach does flips of pure excitement. You turn to your agent and say the magic words: "This is the one. Let's make an offer."
And then, the sudden knot of terror hits your chest:
- How much should we offer?
- If we come in below asking price, will we insult the seller and lose the house?
- If we offer full price, are we getting ripped off?
- What in the world is a CMA, and how much earnest money do we have to wire?
Deciding what to offer on a home is like playing a strategic game of chess. You must balance your genuine emotional excitement with razor-sharp financial calculation, keeping critical negotiation cards close to your chest.
In Chapter 4 of Home Sweet Home: A Step-by-Step Guide for First Time Home Buyers, real estate veteran Sally Street breaks down the exact mechanics of crafting a competitive, protective offer that wins the property without blowing your life savings.
Prefer to watch? Here's the 2-minute version:
1. Finding Fair Market Value: The Comparative Market Analysis (CMA)
The single biggest rookie mistake first-time buyers make is anchoring their offer to the seller's list price.
In real estate, a seller can list their home for whatever imaginary number they desire. A $400,000 listing might be a steal worth $430,000, or an overpriced property truly worth $360,000.
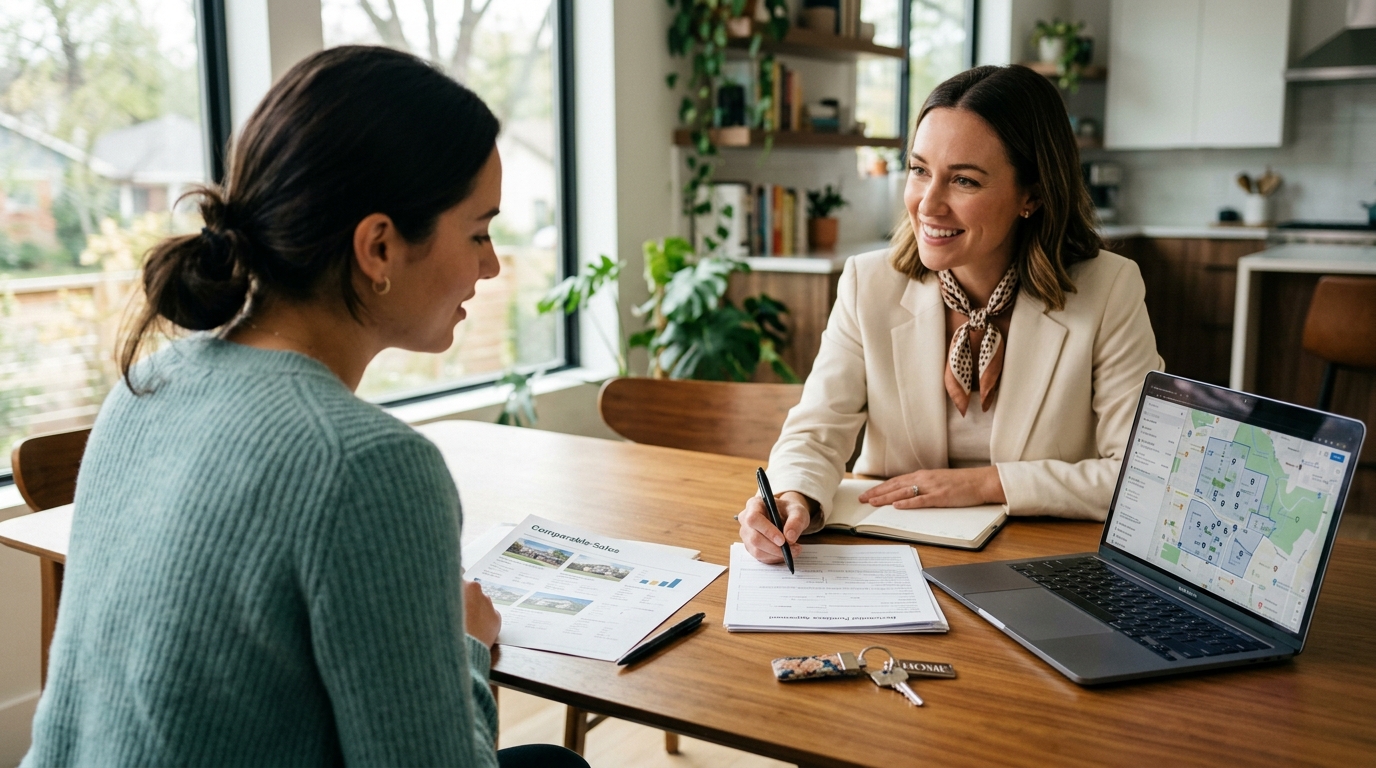
To determine Fair Market Value—what the home is truly worth in today's active market—Sally Street advises using your agent’s secret weapon: The Comparative Market Analysis (CMA).
Fun Fact from Chapter 4: Nationally, homes typically sell for an average of 98% of their asking price—though in heated seller markets, that number frequently pushes above 102%. Reviewing closed comps gives you the empirical proof required to bid with conviction.
2. Earnest Money: The "Skin in the Game" Deposit
When you submit a purchase contract, you must attach an Earnest Money Deposit (EMD).
- What it is: A good-faith cash deposit (typically 1% to 5% of the purchase price) showing the seller that you are serious.
- Where it lives: It does not go to the seller's personal bank account. It is held securely in an independent third-party Escrow Account. At closing, your earnest money is credited directly toward your down payment or closing costs.
- How to protect it: Your deposit is 100% refundable if the transaction falls through due to a valid contractual contingency (like finding catastrophic foundation cracks during an inspection, or loan denial). But if you wake up with cold feet two days before closing and walk away without a contractual reason, the seller keeps your earnest money.
3. The Negotiation Tango: Playing Concessions vs. Price
Negotiating a real estate contract is not just about haggling over the headline number. Sally Street describes negotiating as a tango dance: you have to know when to push, when to give, and what truly matters to the other party.
If a seller refuses to budge on their purchase price, savvy buyers win by negotiating Seller Concessions:
The Seller Priority Audit:
Negotiation is about psychology. Ask your agent to call the listing agent and ask: "Besides price, what terms are most important to the seller?"
- If the seller is building a new home, they might jump at a flexible closing date or a two-week rent-back agreement.
- If the seller inherited the property, they might prioritize a clean, fast close without asking for minor cosmetic touch-ups.
By solving the seller’s logistical headache, you can often beat higher cash offers while protecting your budget.
4. The 3 Non-Negotiable Contract Contingencies
Never sign a purchase agreement without these three legal safety nets:
- Home Inspection Contingency: Gives you 7 to 10 days to hire an independent, licensed home inspector. If the report uncovers $25,000 in dry rot, roof decay, or faulty wiring, you have the legal right to request repairs, negotiate monetary credits, or walk away with your earnest money intact.
- Financing Contingency: Protects you if your mortgage lender encounters an unexpected underwriting hurdle and cannot fund your loan.
- Appraisal Contingency: Protects you if the bank appraiser values the house lower than your offer price. If you offered $350,000 but the home appraises at $335,000, this contingency gives you the leverage to force the seller to lower the price or renegotiate.
5. Bidding War Defense: The Escalation Clause
If you find yourself in a hyper-competitive market facing multiple competing bids, Sally Street recommends discussing an Escalation Clause with your agent.
An escalation clause says: "I offer $300,000 for this home. However, if the seller receives another verifiable, bona fide offer higher than mine, I will automatically outbid them by $2,000, up to a maximum cap of $318,000."
This allows you to win competitive bids without unnecessarily offering your maximum ceiling upfront.
Key Takeaways
- Ignore the List Price: Rely on your agent's Comparative Market Analysis (CMA) of recently closed sales within 200 sq. ft. to determine Fair Market Value.
- Earnest Money Shows Commitment: Budget 1% to 5% for your good-faith deposit, and protect it with ironclad contingencies.
- Negotiate Beyond Price: When sellers stand firm on purchase price, capture value through seller-paid closing costs, rate buydowns, and home warranties.
- Always Protect Your Three Contingencies: Retain inspection, appraisal, and financing clauses to ensure you can exit without penalty if catastrophic flaws emerge.
- Understand the 98% Benchmark: Homes nationally sell near 98% of list price; use market velocity and Days on Market (DOM) to calibrate your opening bid.
Master the Complete Home-Buying Playbook
Ready to turn house tours into accepted offers and closing day celebrations? Get Sally Street's complete masterclass on negotiations, inspections, and closing procedures:
📖 Featured Book: Home Sweet Home: A Step-by-Step Guide for First Time Home Buyers by Sally Street
🏢 Published by: URMS Publishing
🌐 Download Checklists & Offer Worksheets: URMS Bonus Gift Checklists
💬 What is your biggest fear when making an offer on a house? Tell us in the comments below!
We'd Love to Hear From You
"Which insight or framework in this guide resonated with you most? Share your thoughts below!"
Share your feedback or questions with Sally StreetHome Sweet Home: A Step-by-Step Guide for First Time Home Buyers
By Sally Street • URMS Publishing
This practical framework was pulled directly from Sally Street's bestselling guidebook. Master budgets, mortgage programs, contract negotiation, and home inspections without stress.
Never Miss an Insight
Join our VIP Reader Team for weekly frameworks and book giveaways.
Subscribe Free